
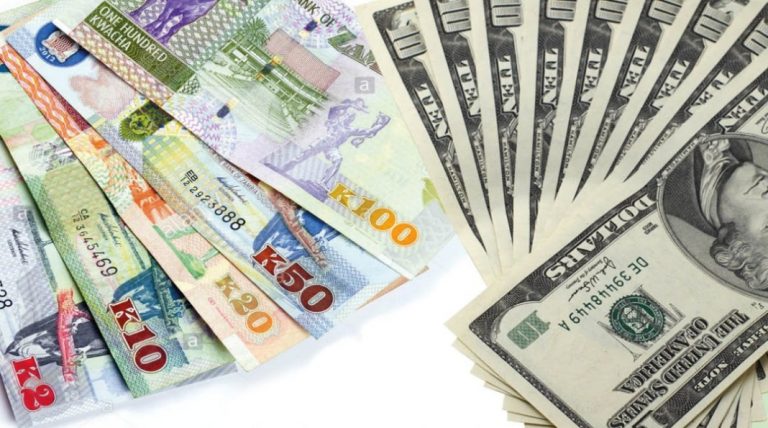
Beyond the Money Sent Home: How Zambians Abroad Support Families and Zambia
Breaking News Zambia
NewsZambians abroad are sending billions of kwacha home, supporting families while contributing to Zambia’s wider economy. But could remittances become an even bigger driver of investment and development? Every month, Zambians living thousands of kilometres from home make a familiar transaction. Money leaves an account in London, Johannesburg, Gaborone, Dubai, New York or elsewhere and […]
Zambians abroad are sending billions of kwacha home, supporting families while contributing to Zambia’s wider economy. But could remittances become an even bigger driver of investment and development?
Every month, Zambians living thousands of kilometres from home make a familiar transaction.
Money leaves an account in London, Johannesburg, Gaborone, Dubai, New York or elsewhere and arrives in Zambia.
For some families, it pays school fees.
For others, it buys food, supports medical treatment, pays rent, helps build a house or keeps a small business operating.
Sometimes it simply helps a family through a difficult month.
These transfers are often described simply as remittances.
But behind every transaction is a much bigger story about the relationship between Zambia and its people abroad.
The numbers are growing
The latest available figures from the Bank of Zambia show that formal inbound international remittances through money transfer operators increased significantly in recent years.
Inbound remittances rose from about K4.99 billion in 2023 to K8.88 billion in 2024, according to the Bank of Zambia’s National Payments Systems data.
The number of inbound transactions also increased from about 1.96 million in 2023 to 2.79 million in 2024.
That means more money was coming into Zambia through formal channels and more transactions were taking place.
The trend continued into 2025.
Bank of Zambia data presented in November 2025 showed inbound remittance credits of US$88.9 million in the first quarter, US$99.7 million in the second quarter and US$103.1 million in the third quarter.
The United States and United Kingdom remained the principal source countries, accounting for 55 percent of inbound remittances in 2025, according to the Bank’s 2025 Annual Report.
The figures tell us something important.
The Zambian Diaspora is already participating in the country’s economy.
But what does the money actually do?
The statistics tell us how much money moves.
They do not always tell us what happens after it arrives.
That is where the human story begins.
A Zambian nurse working abroad may send money every month to support parents at home.
A student in South Africa may receive money from relatives in Botswana.
A professional in the United Kingdom may pay university fees for younger siblings in Zambia.
A family in the United States may finance the construction of a house in Lusaka or a rural hometown.
Someone working in the Gulf may help a relative start a small business.
Another person may send money during an emergency when a family member needs medical treatment.
For the people receiving it, the money is rarely just an economic statistic.
It is school fees.
It is medicine.
It is food.
It is a roof.
It is an opportunity.
And sometimes, it is simply the difference between coping and not coping.
Remittances are also a connection to home
There is another side to the story.
Sending money home is often one of the strongest ways Zambians abroad maintain a practical connection with the country.
Even when someone has lived overseas for many years, they may remain financially connected to parents, siblings, children, relatives or communities in Zambia.
That connection can continue across generations.
A young Zambian born abroad may still participate in supporting relatives in Zambia because the family relationship remains important.
This means the Diaspora should not be viewed simply as a population living outside Zambia.
It is also a network of relationships that crosses borders.
From supporting families to building businesses
But there is an important question Zambia should continue asking:
Can some of the money coming into households also become long-term investment?
There is a significant difference between sending K5,000 home to pay school fees and sending K5,000 to help establish a business.
Both are valuable.
The first supports a family’s immediate welfare.
The second potentially creates an income-generating asset.
This does not mean every remittance should become an investment.
Families have real and immediate needs.
But where a person abroad has surplus funds and an interest in Zambia, there may be opportunities to move from supporting consumption to building assets.
That could include agriculture, property, retail, technology, education, healthcare, tourism or other enterprises.
The challenge is making that process safe and practical.
Trust is part of the equation
For many Zambians abroad, investing back home can raise difficult questions.
Who will manage the business?
Can I trust the person I am sending money to?
Will the accounts be transparent?
What happens if the business fails?
How do I monitor the investment while living in another country?
What are the tax and regulatory requirements?
What happens if there is a disagreement between business partners?
These questions matter.
Someone can have money to invest and still decide not to do so because the perceived risks are too high.
That is why Diaspora investment requires more than encouraging people abroad to “come and invest.”
It requires systems that make investment easier to understand, monitor and manage.
The cost of sending money matters too
Another part of the remittance conversation is the cost of transferring money.
When someone sends money home, the recipient may receive less than the amount the sender originally intended because of transaction fees, exchange-rate differences or other charges.
For a family receiving regular support, even relatively small differences can accumulate over time.
Digital financial services and mobile-based money transfers have expanded the ways people can move funds, while the Bank of Zambia has reported increased remittance activity through formal channels.
The continued growth of formal remittances therefore also raises an important question about how Zambia can make cross-border transfers increasingly efficient, accessible and affordable.
The Diaspora is more than money
There is a danger in reducing the contribution of Zambians abroad to the amount of money they send home.
Money is only one part of the equation.
A Zambian doctor abroad can transfer knowledge.
An engineer can provide technical expertise.
An academic can collaborate with a Zambian university.
An ICT specialist can mentor young developers.
An entrepreneur can connect a Zambian company to an international market.
A professional can create opportunities for someone back home.
And someone who has built a successful business abroad may eventually establish a branch or partnership in Zambia.
This is why the Government’s Diaspora framework identifies not only remittances but also investment, consultation, collaboration, skills transfer and national development as areas of engagement.
The financial connection is therefore only one part of a much larger relationship.
What happens to the money when it reaches Zambia?
This may be one of the most important questions for future research.
How much of Diaspora money goes towards:
Education?
Healthcare?
Housing?
Food and household expenses?
Agriculture?
Small businesses?
Property?
Savings and investment?
There is an opportunity here for better research and better public information.
The more we understand how Diaspora money is used, the better policymakers, financial institutions and the private sector can design products and services around the real needs of Zambians abroad and their families.
From remittances to a Diaspora economy
The future conversation may therefore need to move beyond the question:
“How much money do Zambians abroad send home?”
The bigger question could be:
“What can Zambia build from the relationship it already has with its Diaspora?”
The answer could involve financial services designed specifically for Zambians abroad.
It could involve investment platforms.
It could involve business partnerships.
It could involve professional networks.
It could involve skills-transfer programmes.
It could involve diaspora bonds or other investment mechanisms.
And it could involve creating easier ways for people abroad to establish and manage legitimate businesses in Zambia.
The foundation already exists.
Every school fee paid from abroad, every medical bill settled, every farm supported, every house constructed and every business financed represents a connection between Zambia and its citizens beyond its borders.
The people behind the numbers
Ultimately, remittances are not really about money.
They are about people.
Behind the billions of kwacha are parents supporting children, children supporting parents, siblings helping siblings, families responding to emergencies and Zambians abroad trying to remain connected to the country they call home.
And as Zambia’s relationship with its Diaspora evolves, the conversation should become broader.
It should be about money, yes — but also skills, investment, opportunity, family, identity and belonging.
Because the Zambian Diaspora is not simply sending money home.
It is already part of Zambia’s economic and social story.
The question now is how that relationship can become even more productive for both those abroad and those at home.
Zambia & Diaspora — connecting Zambia with its people wherever they are in the world.
Community Feedback